Lending Beyond the Ordinary: How Britain's Wealthy Borrow Against Everything Except Their Cash
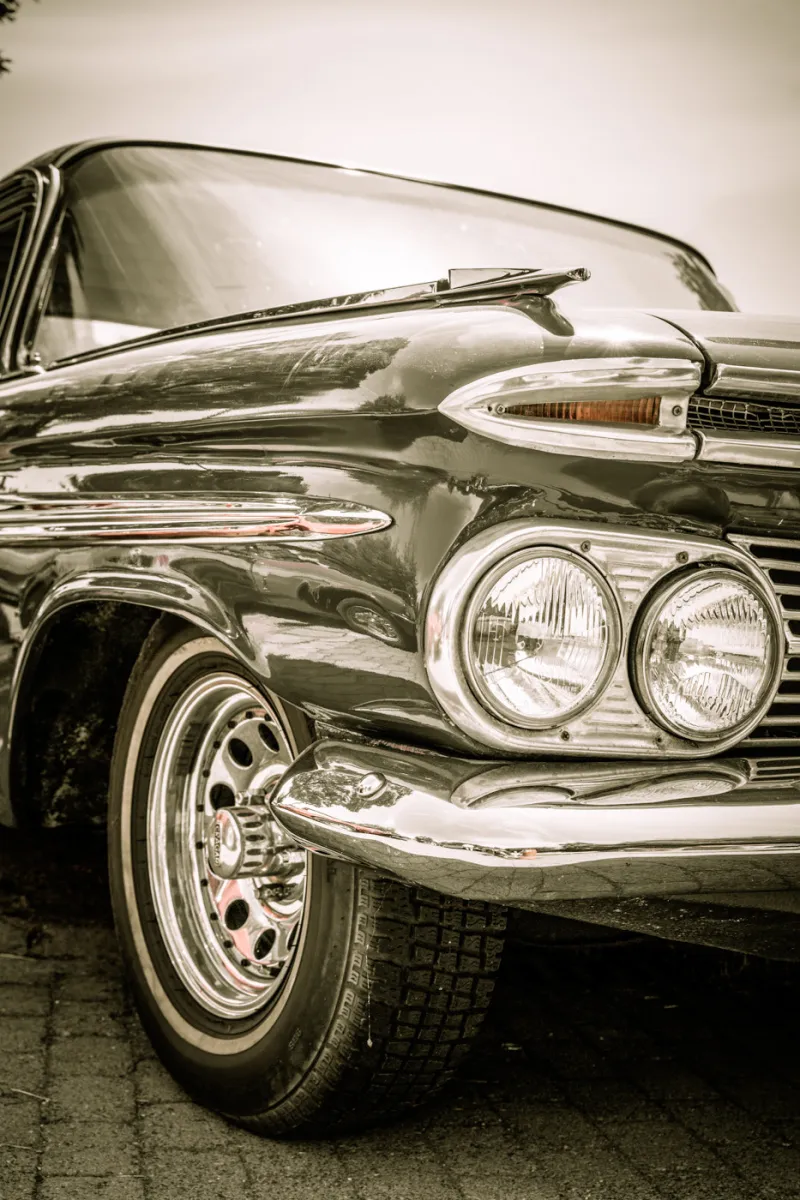
Photo: Markus Spiske Freeforcommercialuse Net, CC BY 3.0, via Wikimedia Commons
To the average borrower, a mortgage is a mortgage: income verified, deposit saved, lender's valuation, done. In the upper reaches of the UK lending market, almost none of that applies. Here, the wealthy borrow against portfolios, paintings, watches and vineyards — often at rates conventional borrowers would envy, and often for reasons that have nothing to do with needing the money.
Understanding how this market works is useful well before one needs it, because the logic behind it illuminates how sophisticated wealth is managed generally.
When Income Doesn't Fit the Box
Start with the mortgage. High-street lenders assess affordability using formulas designed for salaried employees. That model collapses when the applicant is a company director taking a modest salary alongside dividends, a City professional whose compensation is two-thirds deferred bonus, or a founder whose income is, on paper, negligible because their wealth sits in share value.
The private banking and specialist lending market exists precisely for this gap. Rather than formulaic multipliers, these lenders underwrite the individual: they will look at three years of accounts, the trajectory of the business, the structure of share schemes. Some will lend against future carried interest; others will accept a letter from an employer confirming bonus history as sufficient evidence of affordability. Loan sizes routinely run into the millions, and terms — including interest-only structures and bespoke repayment schedules — are negotiated rather than selected from a menu.
The trade-off is scrutiny of a different kind: these lenders want the full picture, and they want a relationship, not a transaction.
Borrowing Against the Portfolio
The second pillar of wealthy lending is the securities-backed credit line. In essence, the client pledges an investment portfolio — shares, funds, sometimes concentrated positions — as collateral, and borrows a percentage of its value, typically between 20 and 70 per cent depending on the volatility of the underlying assets.
The appeal is obvious. Selling investments triggers capital gains tax; borrowing does not. A client facing a £1 million expense can access liquidity without disturbing a portfolio that may be compounding comfortably. The facility can be arranged in days, with none of the friction of a property transaction.
The risk is equally clear, and it is the one that catches people out. If the portfolio falls, the lender issues a margin call: the client must post additional collateral or repay part of the loan, potentially at the worst possible moment. A leveraged position in a falling market converts a paper loss into a forced decision. Anyone using these facilities should size them conservatively and understand the lender's trigger thresholds in writing before drawing a penny.
The Passion Assets
Then there is the most distinctive corner of the market: lending against tangible passion assets. Fine art, classic cars, rare watches and fine wine can all serve as collateral through specialist lenders, typically via short-term facilities at loan-to-value ratios of 30 to 60 per cent.
The mechanics matter here. Art-backed loans usually require the work to be authenticated, appraised and often held in a bonded warehouse or secure storage. Wine lending depends heavily on provenance and storage conditions — a case of Bordeaux with an unbroken chain of custody is collateral; a case from a damp cellar is not. Classic car finance frequently involves the vehicle being held or at least rigorously documented.
These are niche products, usually short-term, and the interest rates reflect the lender's illiquidity risk. They suit someone bridging a timing gap — an art purchase awaiting another sale, for instance — rather than funding ongoing expenditure.
The Common Thread
Across all these structures, one principle recurs: for the wealthy, borrowing is a tool of position management, not desperation. The point is rarely access to cash — the assets are there — but access to cash without disturbing the structure that generates it. That principle, more than any single product, is what separates sophisticated borrowing from expensive borrowing. Handle it well, and leverage extends a strategy. Handle it carelessly, and it becomes the strategy's undoing.