Salt in the Portfolio: What a Superyacht Actually Does to a Balance Sheet
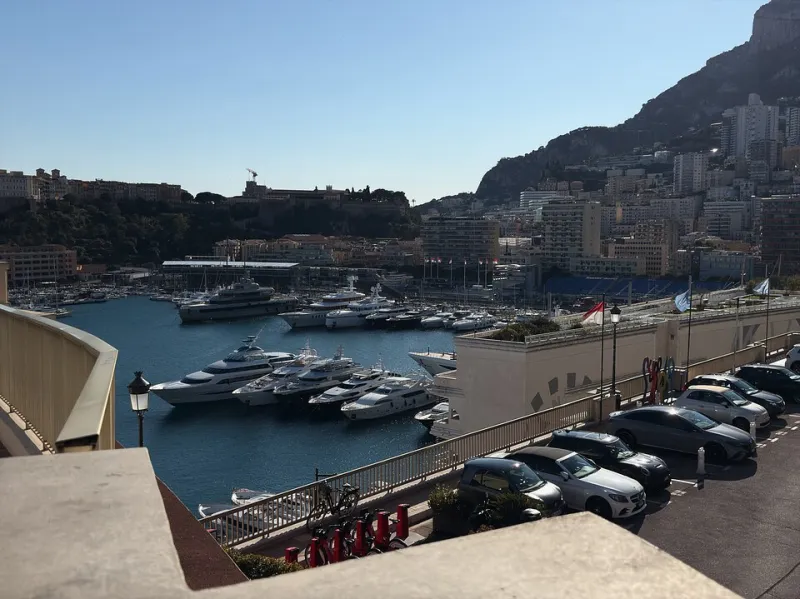
Photo: Mike is Michi, CC BY-SA 4.0, via Wikimedia Commons
There is a particular conversation happening in the meeting rooms of British wealth managers that would have been unthinkable a decade ago. It is not about gilts, or commercial property, or the latest private equity fund. It is about whether a boat — a very large, very expensive boat — belongs in a portfolio at all.
The numbers involved have grown too large to dismiss. Britain now ranks among Europe's most active markets for superyacht ownership, and the questions arriving on advisers' desks have shifted from 'can I afford one?' to 'what does one actually cost me, structurally, over ten years?'
The Depreciation Curve Nobody Puts in the Brochure
Begin with the uncomfortable truth: a superyacht is not an appreciating asset. Unlike prime central London property or a case of fine Burgundy, the typical vessel loses value from the moment of delivery. Brokers estimate that a new superyacht can shed 10 to 15 per cent of its value in the first year alone, with the curve flattening thereafter — provided the boat has been maintained to a standard that keeps it attractive to the next buyer.
The second-hand market punishes neglect brutally. A five-year-old yacht with a complete service history, a respected build yard behind it and an in-demand layout can hold value remarkably well. A poorly specified vessel from an unfashionable yard can become near-unsellable. Marine brokers describe a 'flight to quality' in resale: the market for proven builders — the Dutch yards, the established Italian names — is liquid; the market for speculative builds is anything but.
Against this depreciation, owners can offset running income. Charter revenue is the obvious route, and the UK's tonnage tax regime and various European charter frameworks have made commercial operation more viable than it once was. But no serious adviser presents a yacht as a yield play. The charter income, at best, softens the carrying costs — crew, insurance, berthing and maintenance typically run at eight to ten per cent of the vessel's value annually.
The Isle of Man Structure
This is where the conversation turns from passion purchase to wealth planning. A significant proportion of British-owned superyachts are held through corporate structures registered in the Isle of Man, a jurisdiction with no VAT registration requirement in certain configurations, an established maritime registry and a long institutional memory of shipping law.
The mechanics matter. A properly structured Manx company can own the vessel, employ the crew, manage the charter income and — crucially — provide a clean framework for eventual sale. UK residents must, of course, navigate the tax consequences of any benefit in kind, and HMRC has grown markedly more attentive to 'leisure use' of nominally commercial vessels. Tax specialists interviewed for this piece were unanimous on one point: the structure must reflect genuine commercial substance. A yacht that never charters but claims to be a business is an audit waiting to happen.
VAT is the great variable. A vessel imported into the EU with VAT paid retains its paid status and can move freely; one that is not faces complications every time it cruises French or Italian waters. The difference between the two can be a seven-figure sum at resale.
Fractional Waters
For those deterred by the full commitment, the fractional market has matured. Several operators now sell shares in managed superyachts — typically one-eighth or one-quarter interests — with guaranteed weeks, professional management and, in some schemes, a defined exit route. The economics are essentially those of shared aircraft ownership: you pay for the asset proportionally and the operating costs proportionally, and you surrender a measure of flexibility.
The critique from brokers is consistent. Fractional works well for those who genuinely use two or three weeks a year. For clients who expect to live aboard for a summer, the arithmetic deteriorates, and outright ownership through a corporate wrapper often proves more rational.
So — Boat or Tracker?
The honest comparison is not really a yacht versus a FTSE 100 index fund. Over ten years, the tracker compounds; the yacht, after depreciation and running costs, almost certainly does not. On pure numbers, the tracker wins without contest.
But the wealthy rarely buy yachts for the numbers. They buy them for the hundred hours a year their family actually uses them, for the neutrality a vessel offers as a meeting place for scattered family branches, for the simple fact that the asset delivers experiences no dividend ever will. The correct framing, one tax adviser suggested, is to treat the yacht as consumption with a residual value — and to fund it entirely from income and gains elsewhere in the portfolio.
That, ultimately, is the paradox. A superyacht is a poor investment and a perfectly sensible purchase. The clients who get this right are the ones who never expected the boat to make them money in the first place.